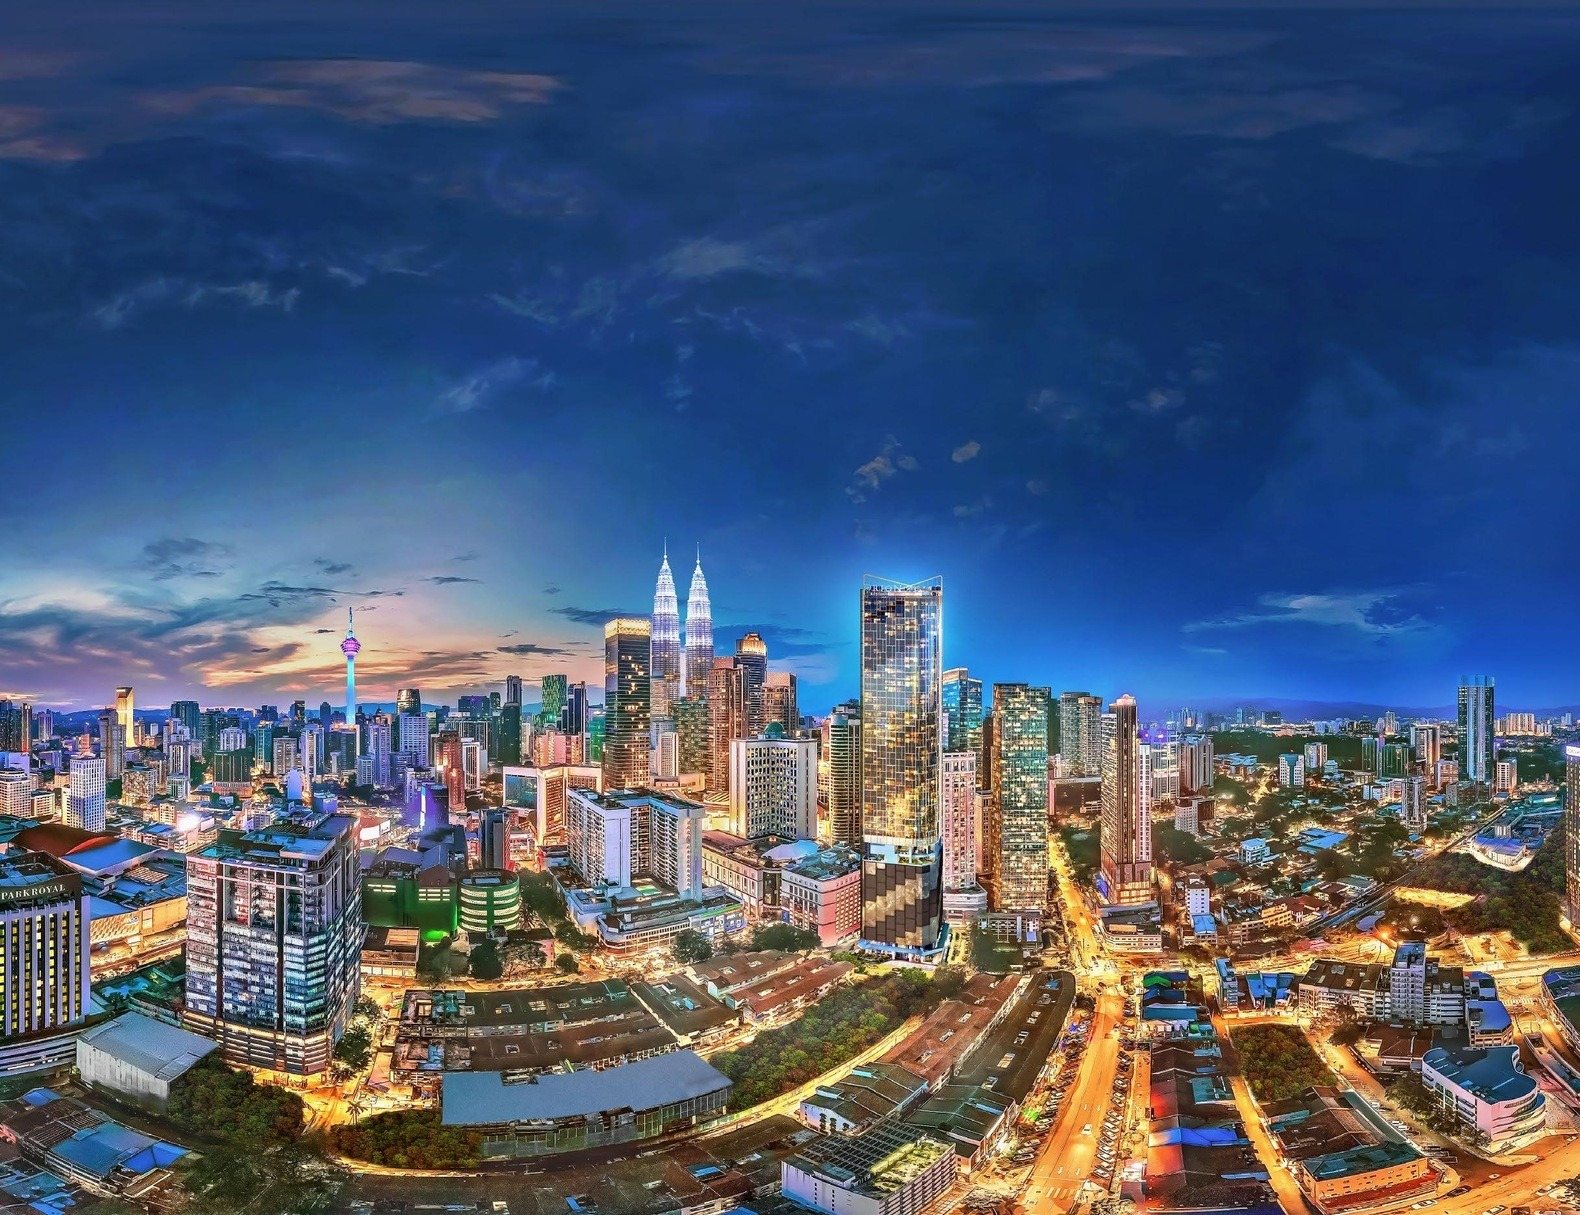
The Ultimate Guide to Foreigner Property Ownership in Malaysia
The short answer
Foreigners can buy residential property in Malaysia, including under freehold title, but every purchase needs state authority consent and must meet a minimum price set by each state. The figures I work with are RM 1,000,000 in Kuala Lumpur and Johor and RM 2,000,000 in Selangor's Zones 1 and 2. They do change, so confirm the current threshold with the state land office or your solicitor.
Malaysia stands out in Southeast Asia as one of the few nations permitting foreigners to own land and residential properties under freehold titles. This regulatory openness, combined with premium global-quality infrastructure, high-yield prospects, and competitive entry prices, makes Malaysia a top-tier destination for international real estate portfolios seeking both capital appreciation and stable rental returns. The nation's strategic regional connectivity—underlined by the Kuala Lumpur International Airport (KLIA) and the upcoming Johor Bahru-Singapore Rapid Transit System (RTS Link)—further enhances its appeal. Investors benefit from a well-regulated property market, transparent transaction processes, and a pro-business environment that actively encourages foreign direct investment.


This guide outlines state-by-state minimum pricing floors, critical tax structures, financing options, and the exact transactional roadmap for an efficient, legally compliant purchase.
1. Regulatory Framework & Ownership Types
Unlike neighboring jurisdictions like Singapore, which impose a highly restrictive Additional Buyer's Stamp Duty (ABSD) and heavily restrict landed titles, Malaysia allows foreigners to acquire both high-rise and landed properties under clear, secure ownership models governed by the National Land Code.
- Freehold Title: Provides absolute, permanent land and building ownership with no expiration date, representing the gold standard for long-term multi-generational wealth preservation.
- Leasehold Title: Grants ownership for a specified period, typically 99 years. Owners can apply to state governments for extensions by paying calculated fractional premium assessments.
- Strata Title: Issued for individual units in multi-story buildings (condominiums, serviced apartments) or gated landed projects with shared developer facilities managed by a Joint Management Body (JMB) or Management Corporation (MC).
- Individual Title: Issued for standalone landed properties (bungalows, semi-detached) where the owner possesses sole title to both physical land and structure.
All foreign acquisitions require State Authority Consent under the National Land Code to ensure regulatory compliance with localized economic policies.
2. State-by-State Minimum Purchase Thresholds
Land is a state matter in Malaysia, so the minimum a foreigner must pay is set by each state, not by one national rule. These are the figures I work with. They do change, so confirm the current threshold with the state land office or your solicitor before you commit to anything.
| State / Territory | Property Type | Minimum Purchase Price | Notes |
|---|---|---|---|
| Kuala Lumpur (Federal Territory) | Confirm with the land office | RM 1,000,000 | The national floor applies. Confirm the permitted property types with the Federal Territory land office. |
| Selangor | Strata only (including landed strata), Zones 1 and 2 | RM 2,000,000 | Zone 1: Petaling, Gombak, Hulu Langat, Sepang, Klang. Zone 2: Kuala Selangor, Kuala Langat. Landed homes on individual title are not open to foreigners. |
| Selangor | Strata only (including landed strata), Zone 3 | RM 1,000,000 | — |
| Johor | Landed homes of two storeys or more; apartments and serviced apartments | RM 1,000,000 | Single-storey and one-and-a-half-storey houses are not open to foreigners. Since 1 July 2025: application fee of RM 2,000 per title, plus an approval levy of 3% of the price (minimum RM 30,000). |
| Penang | Confirm with the land office | Confirm with the land office | Penang sets its own minimum prices, levy and conditions. Confirm them with the Penang land office before committing. |
Ask about the current rules on state consent and real property gains tax in the specific state before you sign. They are not the same everywhere and they have been revised before.
3. Step-by-Step Acquisition Workflow
The acquisition workflow is structured to protect global buyers, governed by the Housing Development Act (HDA) for primary markets and contract law for secondary sales.
- Unit Selection & Reservation: Select your property. For primary projects, pay the developer's booking fee. For secondary sales, pay a 2-3% earnest deposit to a stakeholder lawyer.
- Sales & Purchase Agreement (SPA) Signing: Within 14 to 21 days of reservation, sign the formal SPA and complete the 10% downpayment.
- Applying for State Consent: The buyer’s solicitor applies for State Consent with the State Land Office. How long it takes varies by state.
- Loan Financing Approval: Secure mortgage approval from local or international banks, finalizing the loan and security documentation.
- Progressive Construction Payments: For under-construction projects, banks release progressive disbursements based on certified architectural milestones.
- Handover (Vacant Possession - VP): The developer delivers keys with the Certificate of Completion and Compliance (CCC). This starts the 24-month Defect Liability Period (DLP) for structural repairs.
4. Understanding MM2H (Malaysia My Second Home) Tiers
The MM2H (Malaysia My Second Home) program offers long-term residency. As at September 2026 it has four categories; the figures may change:
- Platinum: USD 1,000,000 fixed deposit and a 20-year pass. You must buy a home of at least RM 2 million, and you may work or run a business.
- Gold: USD 500,000 fixed deposit and a 15-year pass. You must buy a home of at least RM 1 million.
- Silver: USD 150,000 fixed deposit and a 5-year renewable pass. You must buy a home of at least RM 600,000.
- SEZ/SFZ: USD 65,000 (age 21 to 49) or USD 32,000 (age 50 and above) fixed deposit and a 10-year pass, with the purchase in the designated zone.
The minimum age is 25, except for the SEZ/SFZ category as stated. Buying a home is compulsory: the purchase must be completed within 1 year of the pass being endorsed, and the home cannot be sold for 10 years except to upgrade. My MM2H guide has the rest.
5. Financial Leverage & Bank Mortgages
Malaysian banks and international branches offer mortgage options to non-residents under specific prudential limits:
- Debt-Service-Ratio (DSR) Assessments: Each bank sets its own DSR limit — the share of your verified net monthly income that total monthly debt obligations may take up.
- Margin of Finance: Set by each bank; there is no Bank Negara Malaysia cap specific to foreigners. Published MM2H packages go up to 80% to 85% (for example, CIMB up to 85%; RHB 80% plus 5% for legal fees and insurance).
- Interest Rates: Floating home-loan rates are pegged to the Standardised Base Rate (SBR), which follows the Overnight Policy Rate and stood at 2.75% as at September 2026. Major banks' published standard rates are around 3.9% to 4.5%, higher at some banks.
Additional Transactional Costs
- Stamp Duty on the Transfer (MOT): Foreign individuals (not citizens or permanent residents) and foreign-incorporated companies buying residential property pay a flat 8%, on the price or market value, whichever is higher, for transfers executed from 1 January 2026 (it was a flat 4% in 2024 and 2025). Malaysian citizens and permanent residents pay the tiered 1%, 2%, 3% and 4% scale. If you signed the sale and purchase agreement earlier but the transfer is executed after that date, confirm the rate with your lawyer.
- Stamp Duty on the Loan Agreement: 0.5% of the loan amount, for every buyer.
- Legal Fees: Under the Solicitors' Remuneration Order 2023, 1.25% on the first RM 500,000 (minimum RM 500), then 1% on the next RM 7 million. Purchases from a developer use a lower scale.
- Valuation Fees: 0.25% to 0.5% for bank-mandated professional valuations.
- MRTA/MLTA: Mortgage life assurance protecting the outstanding loan balance. It is not required by law, but some banks make it a condition of the loan.
For custom legal guidance, floorplan portfolios, and verified property analysis tailored to your specific investment objectives, consult with Shyan Yee on WhatsApp today. Let’s build your premium portfolio safely and strategically within Malaysia's dynamic real estate landscape.
Frequently Asked Questions
Can foreigners buy land directly in Malaysia?
Foreigners are restricted from buying standalone agricultural land or low-income reserves. Whether landed residential property is open to them depends on each state's rules and minimum price — for example, Johor allows landed homes of two storeys or more from RM 1M, while in Selangor only strata property, including landed strata, is open to foreigners. For Kuala Lumpur and Penang, confirm the permitted property types with the land office.
Is insurance required on home mortgages?
Not by law. MRTA or MLTA protects your mortgage balance in emergencies, and some banks make it a condition of the loan, so check the bank's offer letter.
Written by
REN 46305 · IQI Realty Sdn Bhd · Kuala Lumpur
Licensed real estate negotiator focused on new launches in Kuala Lumpur, Selangor and Johor Bahru. Articles draw on developer material and site visits; prices and rules change, so confirm the latest before you buy.
Related articles
Need Personalized Advice on Malaysian Real Estate?
Speak with licensed senior agent Shyan Yee (REN 46305) for MM2H property consultations, state consent processing, and curated project shortlist.
WhatsApp Shyan Yee (+60 17-279 8932)